Start with your plan.
Contact our team to ask about coverage. Have your insurer and plan name ready; ask how to provide any insurance documents securely.
 Book an appointment
GENESIS MED / HBOT INSURANCE COVERAGE
Medical-grade hyperbaric oxygen therapy, with most major insurance accepted. Let’s find out what your plan could cover.
For eligible patients with approved coverage and no remaining patient responsibility. Your cost depends on your benefits, network, deductible, copay, and coinsurance. $0 is possible, not guaranteed.
Check my coverage Explore covered conditions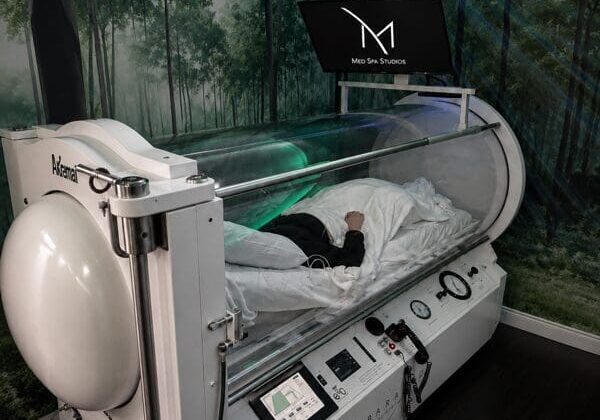
LET’S START WITH YOUR PLAN
We accept most major insurance plans. From employer coverage to individual plans, speak with our team about using your benefits for medically necessary HBOT.
MAJOR U.S. INSURANCE BRANDS · EXACT PLAN VERIFICATION REQUIRED
 UnitedHealthcare
 Blue Cross Blue Shield
 Aetna
 Cigna Healthcare
 Humana
 Anthem
 Kaiser Permanente
 Molina Healthcare
 Ambetter Health
 Wellcare
 Oscar
These brands identify major insurers, not a guarantee that every product is accepted or in network. Blue Cross Blue Shield companies are independent; HMO, Kaiser, and out-of-state plans may restrict care outside their networks. Confirm your exact plan before scheduling.
Medicare, Medicare Advantage, Medicaid & TRICARE
Ask about your specific program, managed-care plan, referral requirements, and provider eligibility. Benefits and participation vary.
UNDERSTAND YOUR OPTIONS
Coverage starts with a qualifying diagnosis and medical necessity. Explore the conditions recognized in Medicare and major commercial policies. Our medical team can discuss suitability and the appropriate setting for your care.
Listed in Medicare’s national HBOT policy. Each has clinical requirements; a diagnosis alone does not establish coverage.
Read the Medicare policyDiabetes-related wounds at Wagner grade III or higher, with no measurable healing after at least 30 days of standard wound care. HBOT supplements ongoing wound care; continued coverage requires documented healing at 30-day reviews.
Osteoradionecrosis: radiation-damaged bone, treated alongside conventional care.
Soft tissue radionecrosis. Commercial policies also specify radiation cystitis (bladder injury) and proctitis (rectal injury).
Refractory osteomyelitis that persists despite conventional medical and surgical management.
Preservation of a failing graft; not routine treatment of an uncomplicated wound.
An injury severely restricts blood supply to a limb. HBOT accompanies standard treatment when function, the limb, or life is threatened.
Severely injured or surgically reattached tissue with threatened survival; HBOT is an adjunct to urgent surgical and trauma care.
Sudden loss of arterial circulation. Aetna specifies emergency intervention and imaging evidence of a clot or embolus.
Rapidly destructive tissue infections, including necrotizing fasciitis; used alongside surgery and antibiotics.
A serious clostridial infection that destroys muscle and requires urgent medical and surgical treatment.
Carbon monoxide exposure that requires medical assessment for chamber-based oxygen treatment.
Illness related to pressure changes, often associated with diving, requiring urgent specialist assessment.
Air or gas bubbles obstruct circulation; this is an emergency indication.
Acute toxic exposure. Cigna specifies HBOT after an antidote; UnitedHealthcare specifies associated carbon monoxide poisoning.
Persistent bacterial infection despite antibiotics and surgery. Medicare includes adjunctive HBOT; some commercial policies exclude it.
Some commercial policies cover these indications or specific situations. They are not additional blanket Medicare benefits. Open a condition for details and the relevant policies.
Sudden inner-ear hearing loss. Severity, prior steroid treatment, and time since onset matter; thresholds differ by insurer.
A blocked artery to the retina causing sudden vision loss. Requires emergency assessment; timing is critical.
Bone damage from inadequate blood supply. Listed by Aetna, UnitedHealthcare, and Cigna; stage and plan criteria apply.
Exceptional blood loss when transfusion cannot be given, or under some policies is delayed or refused.
Selected deep second- or third-degree burns. Some policies require inpatient hospitalization.
Infection within the skull, with HBOT considered as part of specialist care.
Dangerous pressure within a muscle compartment restricts circulation; urgent surgical assessment comes first.
Surgically moved tissue showing reduced circulation or threatened failure, rather than routine postoperative recovery.
Selected preventive treatment before and after dental surgery; the planned site and radiation history must meet policy criteria.
Gas-filled cysts in the bowel wall. Aetna lists this indication; many other policies do not.
Anthem lists narrow exceptions involving persistent hypoxia after revascularization, failing grafts/flaps, radiation injury, or serious infection. Its venous-ulcer criteria require graft/flap support, arterial disease, and unresolved hypoxia. Continued treatment requires measurable healing. These are not blanket wound benefits.
Cigna also lists bleeding bladder inflammation resulting from a chemolytic response or graft-versus-host disease; individual review is required.
This guide summarizes the policies linked here, not every U.S. plan. Covered uses, prior authorization, and treatment limits vary. General wellness, anti-aging, and routine recovery are not automatically covered HBOT indications.
CLARITY BEFORE CARE
Contact our team to ask about coverage. Have your insurer and plan name ready; ask how to provide any insurance documents securely.
Discuss your diagnosis with the medical team. Confirm network status, medical-necessity documentation, referrals, and any required prior authorization.
Ask for an estimate before treatment, including any deductible, copay, or coinsurance. Benefit verification and authorization do not guarantee claim payment.
As low as $0 with insurance, when your approved benefits cover the full cost.
COVERAGE SOURCES / RESEARCHED SEPTEMBER 22, 2026
Policies can change. Your current benefit documents and insurer’s decision govern coverage. Insurer names and logos belong to their respective owners and do not imply endorsement.
START A CONVERSATION